Article
Key takeaways from little sandy coal R&D tax credit appeal
April 13, 2023 · Authored by Travis Riley and Josh Harbin
The U.S. Court of Appeals for the Seventh Circuit issued its opinion in Little sandy coal company, Inc. V. Commissioner of internal revenue on March 7, 2023.
The decision reads, in part, “We disagree with some aspects of the tax court's reasoning, but ultimately, Taxpayer claimed more tax credit than it could prove.”
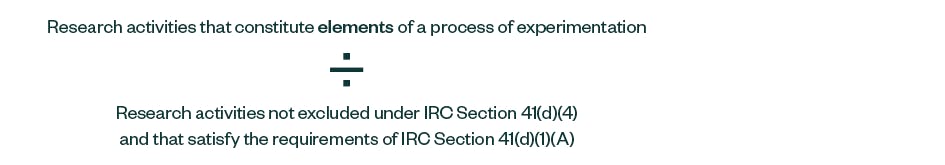
Although the appeals court affirmed the tax court’s decision in favor of the IRS, the case can be generally viewed as more favorable to taxpayers in terms of the appeals court’s evaluation of the substantially all rule contained in Internal Revenue Code (IRC) Section 41(d)(1)(C).
Background
Little Sandy Coal Company, the taxpayer, claimed IRC Section 41 research tax credits for the design and construction of 11 first-in-class vessels during its tax year ended June 2014. Upon review, the IRS disallowed the tax credits and the taxpayer subsequently petitioned for redetermination by the U.S. Tax Court.
For the tax court trial, the parties agreed to review two of the vessels as representatives for the relevant issues: tanker and dry dock.
The tax court held, in part, that providing services in direct supervision or support of research isn’t engaged in research and thus such activities cannot constitute elements of a process of experimentation for purposes of the substantially all rule.
Further, the tax court held that because Little Sandy Coal didn’t meet its burden of proving substantially all its research activities constituted elements of a process of experimentation, none of the expenses incurred were qualified research expenses.
While the appeals court affirmed the ultimate decision noting the taxpayer “failed to provide a principled way to determine the portion of employee activities that constituted elements of a process of experimentation,” it disagreed with the tax court’s holding that direct supervision and support of research couldn’t constitute elements of a process of experimentation.


Chemical manufacturer benefits from Baker Tilly’s approach to organizational readiness
The information provided here is of a general nature and is not intended to address the specific circumstances of any individual or entity. In specific circumstances, the services of a professional should be sought. Tax information, if any, contained in this communication was not intended or written to be used by any person for the purpose of avoiding penalties, nor should such information be construed as an opinion upon which any person may rely. The intended recipients of this communication and any attachments are not subject to any limitation on the disclosure of the tax treatment or tax structure of any transaction or matter that is the subject of this communication and any attachments.