Article
Discover tax savings with the new energy efficient home section 45L tax credit
April 23, 2024 · Authored by Kyle Sund and Matt Lord
Since publication of this article, the Section 45L tax credit was modified by the One Big Beautiful Bill Act (OBBBA) of 2025, which terminated the tax credit for residential units first sold or leased after June 30, 2026.
Real estate developers and homebuilders who want to reduce their tax burden, and contribute to a greener future in the process, should consider an Internal Revenue Code (IRC) Section 45L tax credit. The following will provide an overview of the credit, its value, eligibility requirements, and the certification process.
What is the section 45L tax credit?
The Section 45L tax credit rewards developers and homebuilders who construct or renovate single family homes, multifamily properties, and manufactured homes that meet the minimum energy-efficiency standards prescribed by ENERGY STAR.
Section 45L of the IRC went into effect in 2006 to incentivize new construction or substantial renovation of energy-efficient single-family homes and multifamily properties.
The Inflation Reduction Act of 2022 implemented significant changes to the Section 45L tax credit.
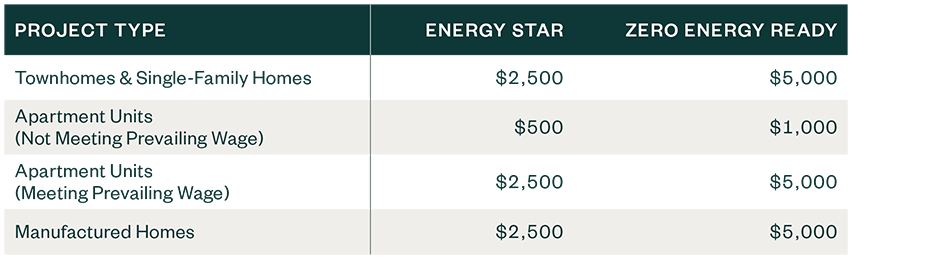
Effective Jan. 1, 2023, the Section 45L tax credit is available to homebuilders and developers through 2032. The credit ranges from $500 to $5,000, per residential dwelling unit, based on the following criteria:
- Type of development

Related sections
The information provided here is of a general nature and is not intended to address the specific circumstances of any individual or entity. In specific circumstances, the services of a professional should be sought. Tax information, if any, contained in this communication was not intended or written to be used by any person for the purpose of avoiding penalties, nor should such information be construed as an opinion upon which any person may rely. The intended recipients of this communication and any attachments are not subject to any limitation on the disclosure of the tax treatment or tax structure of any transaction or matter that is the subject of this communication and any attachments.